Most people spend decades saving for retirement inside accounts like a 401(k), traditional IRA, or 403(b). These accounts feel like a win because they let you delay paying taxes on the money you contribute. But there’s a catch that many savers don’t fully appreciate until it’s time to actually use the money. Every dollar you pull out later is taxable, and nobody knows what tax rates will look like down the road — and most people think they’ll be higher.
That’s where the idea of a strategic rollout comes in.
Note we said rollout, not rollover.
A traditional rollover is when you move money from a tax-deferred 401(k) into another tax-deferred account like an IRA.
That’s like getting out of the frying pan and into the fire.
Instead, you want to do a strategic rollout.
This means instead of leaving all your money sitting in a tax-deferred account and hoping tax rates stay reasonable, a strategic rollout is a planned, step-by-step way of moving that money into a more tax-friendly position over time. Done thoughtfully, it can help you keep more of what you’ve saved and give you more predictable income later on.
Here’s what it is, why it matters, and how everyday families think about it.
The Three Buckets
Sometimes it helps to step back and take a big-picture look at the main “buckets” you can put your money in when setting it aside for the future:
Bucket #1 – Taxed-As-Earned – These are vehicles like a regular savings or brokerage account. You pay taxes on the interest and gains.
Bucket #2 – Tax-Deferred – These are vehicles such as your traditional 401(k) or IRA. You get a tax break on contributions, but you pay taxes on 100% of what you withdraw later.
Bucket #3 – Tax-Advantaged – This includes vehicles like Roth accounts and certain properly structured life insurance policies. Money in this bucket has already been taxed, and if the rules are followed, future growth and distributions can be tax-free.
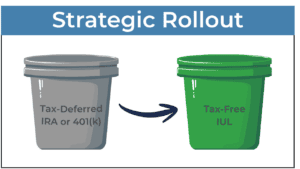
A strategic rollout usually involves moving money from the second bucket into the third bucket — particularly into a properly structured, maximum-funded Indexed Universal Life policy (what we call an IUL LASER Fund) — one careful step at a time.
What “Tax-Deferred” Really Means
The term “tax-deferred” simply means “tax later.” You don’t skip the tax bill. You postpone it — often to a time when you could end up paying more in taxes.
Every dollar in a traditional 401(k) or IRA has never been taxed. Once you retire and start taking withdrawals, the IRS finally gets its cut. And after you reach a certain age, the government actually requires you to start pulling money out, whether you need it or not. Those forced withdrawals are called Required Minimum Distributions, or RMDs.
Here’s the part that catches people off guard. If your account has grown nicely over the years, your future withdrawals could push you into a higher tax bracket than you expected. Larger withdrawals can also affect how much of your Social Security gets taxed and can bump up what you pay for Medicare.
In other words, a big tax-deferred balance can quietly become a big tax problem.
A Better Option – The Strategic Rollout
A strategic rollout is a way to incrementally move money out of a tax-deferred account, get the taxes over with in measured amounts, and reposition the money in a vehicle where it can grow and be accessed tax-free, like a properly structured, maximum-funded Indexed Universal Life (what we call an IUL LASER Fund).
This isn’t about yanking all your money out at once and getting hit with a giant tax bill. It’s about doing it in slices, year by year, in a way that fits your specific tax situation.
Access, Protection, and Predictability
Beyond taxes, a strategic rollout is often about three other priorities that matter deeply to families.
Liquidity – When done right, moving your money to an IUL can then give you access to some of your money tax-free when you need it.
Market Protection – Money inside an IUL is shielded from losses during market downturns with a guaranteed 0% floor. Compare that to IRAs and 401(k)s, where you could watch your account value fall by as much as 40% — which millions of Americans did in 2008.
Predictable Rates of Return – While nothing is guaranteed, with IUL’s historic average returns of 5% to 10%, you can have a reasonable idea of what your tax-free retirement income with the policy could look like, instead of guessing what the market or the tax code will do to you.
When you reposition money into vehicles like an IUL, you’re building a more secure, tax-free financial future.
Why Timing Matters
Optimizing your strategic rollout is about timing. Tax rates aren’t fixed forever. They go up and down based on decisions made in Washington. Many financial educators point out that today’s tax rates, from a historical perspective, are relatively low. Whether they stay that way is anyone’s guess.
If you believe taxes could be higher in the future, paying some tax now on a portion of your retirement money, at today’s known rates, may make more sense than gambling on unknown future rates.
There are also personal windows of opportunity. For example, the years between when you stop working and begin Social Security are often lower-income years than when you have to start taking RMDs. That can create a chance to move money out of a tax-deferred account while you’re in a lower bracket.
If done correctly, it’s also possible to stay within your same tax bracket, using any room you have between your total taxable income and the top threshold of your current tax bracket. It’s also possible to move a greater volume of money out during tax-advantaged years (whether that’s because of current tax laws, tax deductions, or personal income situations).
A Simple Example
Picture a couple in their early 60s with a sizable IRA. If they leave it alone, in a few years, RMDs could push them into a higher bracket and cause more of their Social Security to be taxed.
Instead, they work with a qualified advisor and plan to move a set amount out of the IRA each year for several years. They pay the tax on each slice at the current rate. The money then goes into an IUL where it has the opportunity to grow tax-free and be accessed tax-free via policy loans in retirement.
They didn’t avoid taxes. They chose when and how to pay them, on their own terms.
The Bottom Line
A strategic rollout isn’t a trick or a loophole. It’s simply a thoughtful plan for handling the tax bill that is already waiting for you inside your retirement accounts.
The right approach depends on your income, your goals, your family, and your timeline. A decision like this deserves a real conversation with a qualified IUL specialist who understands your full picture.
Still, the concept itself is worth understanding. Because in retirement, it isn’t just what you save that matters. It’s what you get to keep.
Ready to Step Into a Brighter Future?
Start your IUL exploration today—access our free books, attend our educational webinars, or connect with a Certified Laser Fund Professional right here.
*Policy performance and/or experiences are shared for educational use only and do not predict or guarantee actual or future results.
_______________________
Watch Doug Andrew give a quick overview of these concepts on his YouTube channel…
Chapter 1: Introduction 0:00 0 seconds how to use iul for Ira 401K qualified plan strategic rollouts 0:10 10 seconds so this episode is going to talk about strategic rollouts it’s not a rollover a rollover is like going from the frying 0:18 18 seconds pan into the fire so to speak uh rollovers are what most people hear when they’re told hey take the money in your 0:26 26 seconds 401ks roll that money over to an array and keep uh deferring postponing 0:34 34 seconds procrastinating until you’re age 72 if you don’t need the money and then take rmds required minimum distributions 0:42 42 seconds thinking you’re saving tax that is the worst advice for most Americans it’s not saving tax it’s actually compounding 0:50 50 seconds increasing the tax they might be paying the least amount of tax in each given year but when it’s strung out over their life expectancies they’re shocked with 0:59 59 seconds how much tax they ended up paying instead you should do a strategic roll out get the money out of those iray of 1:06 1 minute, 6 seconds 401k strategically usually in 5 years and get the taxes over and done with sooner than later and reposition it into something that’s going to be 1:15 1 minute, 15 seconds taxfree from now on a properly structured ilul get ready you’re going to be blown away with what I showed you Chapter 2: Benefits of Strategic Rollouts 1:22 1 minute, 22 seconds so I’m Doug Andrew and what do I know well I’ve been a financial strategist and retirement planning specialist now for five decades helping thousands of 1:31 1 minute, 31 seconds people optimize assets minimize taxes and Empower what I call their authentic wealth but I’ve helped many people prepare for a comfortable retirement uh 1:40 1 minute, 40 seconds to not outlive their money and eliminate the dangers of taxes inflation and Market volatility on their hard-earned 1:47 1 minute, 47 seconds uh and saved money and most Americans have way too much money and yet to be taxed IAS and 401ks invested in the 1:56 1 minute, 56 seconds market so let me show you why I usually recommend a strategic rollout and why 2:03 2 minutes, 3 seconds it’s wise to do this so as we look at this uh strategy and we want to help people optimize those assets uh what 2:11 2 minutes, 11 seconds we’re wanting to do is use tax efficient strategies wealth transfer strategies okay and this is why we train uh IL Chapter 3: Tax-Efficient Strategies 2:21 2 minutes, 21 seconds agents how to become sophisticated retirement planning specialist by doing this now in my book the laser fund which 2:28 2 minutes, 28 seconds is flying off of our Ware house shelves and if stay with me to the end of this episode I’ll gift you a free copy of this on Amazon you’re going to pay 20 to 2:36 2 minutes, 36 seconds 70 bucks for it and I’ll GI you a copy free if you’ll just contribute towards the shipping okay so in the last chapter of the uh left brain side of the book 2:45 2 minutes, 45 seconds because this is actually two books in one this is the left brain side this is the right brain side the stories now in 2:51 2 minutes, 51 seconds the 14th chapter I talk about the four categories or resources that a lot of Americans May draw retirement income 2:59 2 minutes, 59 seconds come from not everybody does from all four but uh the the biggest one is investment income this is usually money 3:07 3 minutes, 7 seconds and I raise a for1 Cas uh a lot of people own real estate thinking oh I’m going to get rental income and so forth 3:13 3 minutes, 13 seconds but then they end up regretting that because they don’t like being a landlord uh in their older years taking out trash 3:22 3 minutes, 22 seconds and fixing toilets evicting tenants some like doing that but most don’t uh then you have the guaranteed income people these are those who like guarantees uh 3:31 3 minutes, 31 seconds they they’re not so worried about being rich they just don’t want to be poor and so they’re fine with just having a guaranteed income out of a pension or 3:39 3 minutes, 39 seconds Social Security maybe in an annuity okay uh this is the most underutilized and this is the taxfree category uh it’s the 3:46 3 minutes, 46 seconds least understood and uh the most impactful this is uh where I recommend people have 40 to 60% of the income so 3:54 3 minutes, 54 seconds let’s dive a little bit deeper the purple bucket uh where I think most Americans are way too topheavy they have 4:03 4 minutes, 3 seconds way too much money in this one when they retire and at retirement planning is totally different than what you did for retirement but it’s an money trapped in 4:12 4 minutes, 12 seconds my opinion and yet to be taxed I razor 401ks invested in the market and Wall Street was not designed to create predictable income that’s why we have in 4:20 4 minutes, 20 seconds the financial services industry a pathetic 4% rule they only want you to pull out 4% a million dollars they only want you to pull out 40,000 and then you 4:29 4 minutes, 29 seconds have to to pay tax on that even in a 25% bracket you’re only netting 3% or 30,000 that’s pathetic and so I have to get 4:38 4 minutes, 38 seconds people uh to consider getting money out of this purple bucket down to the green bucket I’ll come back to that some 4:45 4 minutes, 45 seconds people own real estate but like I said some are sick and tired of being landlords and uh yet they feel stuck because they’ve been doing 1031 4:52 4 minutes, 52 seconds exchanges uh deferring deferring and they’re going to have to pay a huge capital gain tax but now they’re realizing tax revenue rers are proposing 5:01 5 minutes, 1 second doing away with those 1031 exchanges and the step up and basis on long-term capital gains and all kinds of things because they’re hard up for tax dollars 5:09 5 minutes, 9 seconds and so uh many times I show them just by biting the bullet uh selling the real estate uh paying the the 20% capital 5:17 5 minutes, 17 seconds gain tax and taking the net and putting it into an i and they’re shocked when the income out of the iul uh is uh not 5:26 5 minutes, 26 seconds only equal to but of times greater than the in they were getting out of their properties and they don’t have to be a landlord anymore they’re they’re Chapter 4: Advantages of IUL Over Other Investments 5:34 5 minutes, 34 seconds surprised okay uh some people like the guaranteed income based on risk tolerance the most underutilized uh my 5:41 5 minutes, 41 seconds favorite is the green bucket you might have roths in there you might have municipal bonds but my favorite is a Max 5:48 5 minutes, 48 seconds funded tax Advantage insurance contract if it’s structured correctly and funded properly an IL is deemed a laser fund 5:55 5 minutes, 55 seconds okay and so it knocks the socks off of a Roth okay roths only have two basic 6:03 6 minutes, 3 seconds advantages um iul has those two advantages and four additional advantages that roths will never have so 6:10 6 minutes, 10 seconds I will never own an IR rare 41k up here and I will never own a Roth um and I never have because I can have all the 6:19 6 minutes, 19 seconds benefits of a Roth and a whole bunch more with my money and an IL and I explained that in other episodes on this 6:27 6 minutes, 27 seconds channel and so this is my favorite buck it requires most of my clients do a strategic 6:34 6 minutes, 34 seconds rollout from the purple bucket down to the green bucket but I would recommend at at retirement that no more than 30% 6:42 6 minutes, 42 seconds of a person’s income is is coming out of the purple bucket and once people read my book they they don’t want any of their money left in that bucket I would 6:50 6 minutes, 50 seconds recommend that no more than 30% of your income should be relying upon your real estate uh because real estate goes through volatility I would recommend 6:59 6 minutes, 59 seconds based on risk tolerance that zero to uh up to 80% of your income could be guaranteed income but this one down here 7:08 7 minutes, 8 seconds I recommend that 40 to 60% of your retirement income be totally taxfree what does that mean the IRS will know 7:16 7 minutes, 16 seconds you’re receiving it but it it doesn’t show up anywhere on your 1040 tax return it’s totally taxfree it’s that simple okay and money out of an i does not show 7:24 7 minutes, 24 seconds up on your 1040 tax return un unless you take it out the stupid way I explain how to do it the smart way in my book so 7:31 7 minutes, 31 seconds looking at this in my book the laser fund I give some hypothetical example so that people will get it probably my 7:40 7 minutes, 40 seconds favorite is Mr Tax to the max versus Mrs ival lot Moore and in this example uh tax to the max follows the herd and he 7:48 7 minutes, 48 seconds listens to CNBC and he uh doesn’t need the money at age 59 and a half when he can avoid the 10% penalty and he gets 7:56 7 minutes, 56 seconds convinced to keep uh deferring and deferring till he’s age 72 and then he’s convinced to take rmd he’s thinking he’s 8:04 8 minutes, 4 seconds saving tax no he’s compounding the tax I developed sof software years ago that would show people the darkness of the night so to speak if they did that and 8:13 8 minutes, 13 seconds if they took rmds from age 72 out to their life expectancy their spouse’s life expectancy and then down to their 8:20 8 minutes, 20 seconds children who inherit it to uh and they have to get it out now in 10 years they can’t keep it to their life expectancy people are flabber GED when 8:30 8 minutes, 30 seconds they see how much tax they end up paying it’s usually conservatively as uh they will pay in tax by stringing it out as 8:39 8 minutes, 39 seconds much as they have in their Accounts at age 60 65 or 70 they’re going to pay 8:46 8 minutes, 46 seconds that much in tax by continuing to postpone and uh then I showed them Mrs IA lot Mo who does a strategic rollout 8:53 8 minutes, 53 seconds over five years and pays way less tax and ends up with double double the 9:01 9 minutes, 1 second income and we do this all the time it’s really a conservative example I also have another one in my book called The 9:07 9 minutes, 7 seconds Smiths versus the Jones same scenario uh I end up getting the money out of their IR at 401ks with no tax over a 10year 9:16 9 minutes, 16 seconds period by resurrecting deductions that they had been killing on their real estate uh but we double the net spendable income and uh they’re they’re 9:25 9 minutes, 25 seconds have they have much greater liquidity safety rate of return we’ve optimized their assets so those are hypothetical stories that you can read in the book 9:32 9 minutes, 32 seconds that I want to gift you and uh there’s articles I used to write newspaper articles showing the difference between tax to the max versus Mrs live a lot 9:40 9 minutes, 40 seconds more and people would just fill up my seminars to come and learn how this could apply in their particular set of 9:47 9 minutes, 47 seconds circumstances uh but then in my book I I do talk about the strategy and I give real life stories so in a nutshell a 9:54 9 minutes, 54 seconds strategic roll out is up to a three-part strategy you don’t have to do all three the first step is you 10:02 10 minutes, 2 seconds strategically reposition your retirement monies I rais 401ks and so forth over five maybe 10 years subjecting that 10:09 10 minutes, 9 seconds money to tax getting the taxes over and done with sooner than later they’re showing up on the front page of your 1040 tax return but you’re making an 10:17 10 minutes, 17 seconds assumption that your current tax bracket is likely the lowest bracket you will ever be in and most Americans are coming to that realization and number two uh Chapter 5: Step-by-Step Guide to Strategic Rollouts 10:27 10 minutes, 27 seconds assumption is that uh uh money will never be worth more than is more than it is today because of inflation so it’d be 10:34 10 minutes, 34 seconds better to pay taxes uh on today’s dollars in tomorrow’s dollars and enjoy taxfree money down the road and so once 10:41 10 minutes, 41 seconds you understand that you do a strategic rollout analysis and that determines the bucket size of the 10:48 10 minutes, 48 seconds IL now uh the second part of this is is you’re going to reposition the after tax money as you’re rolling it out uh and 10:57 10 minutes, 57 seconds you’re going to put that into an IL so if you have somebody that has 300,000 and yet to be taxed I of 401ks and 11:04 11 minutes, 4 seconds they’re in a 33% bracket if they pull out 300,000 they’re going to net 200,000 you put 200,000 into the I 401ks and it 11:12 11 minutes, 12 seconds will generate more income than the after tax money you take out of an IRA 401K is this making sense or sometimes Savvy 11:21 11 minutes, 21 seconds people I had a a guy that had 500,000 he was in a 40% bracket he pulled out 500,000 and one Fell Swoop paid 200,000 11:28 11 minutes, 28 seconds in tax and put the net of 300,000 into an insurance policy but he didn’t he didn’t need it so he wanted to maximize what he left behind so he got ended up 11:36 11 minutes, 36 seconds with a $1.5 million death benefit now when he dies he leaves behinds a million and a half taxfree instead of 300,000 11:44 11 minutes, 44 seconds after tax in an IRA 401K he five times what he was going to leave behind does that make sense uh or other examples 11:53 11 minutes, 53 seconds that I’ll go through here in just a moment now the third strategy is if you can offset some or all of the tax you 12:01 12 minutes, 1 second pay during the rollout uh by creating or resurrecting deductions that maybe you killed that’s 12:08 12 minutes, 8 seconds icing on the cake and many times I have done this and those are the stories like the Smiths and the Jones but I’ll show you an actual example of this here in 12:17 12 minutes, 17 seconds just a moment so the real stories that I give in the book uh a a couple of school teachers husband and wife a real estate 12:25 12 minutes, 25 seconds landlord a husband and wife that were both Physicians we saved them 1.2 Mill million a couple in California we took from the highest tax bracket to a 0% tax 12:33 12 minutes, 33 seconds bracket in 5 years so let me give you just a little bit more detail one by one uh the husband and wife both School teachers came to me and they had a 12:42 12 minutes, 42 seconds quarter of a million dollars there at age 59 and a half accumulated in their 401ks and 403bs this was years ago and 12:49 12 minutes, 49 seconds their advisor had been telling them well you don’t need the money so keep deferring until you’re age 70 and a half back then uh you had to start taking r 12:59 12 minutes, 59 seconds MDS at age 70 and a half now it’s age 72 so I gave them an illustration if they did that if they took that quarter of a 13:06 13 minutes, 6 seconds million and they kept earning a rate of return of 7.2% uh it would double to 500,000 and if they took out rmds uh throughout the 13:15 13 minutes, 15 seconds husband’s life expectancy the wife’s life expectancy and down to their kids they were shocked at a minimum they would pay a quarter of a million dollar Chapter 6: Case Study: Tax Savings 13:23 13 minutes, 23 seconds in tax they said we’re going to end up paying as much in tax as we have Sav so far Accord a million I said yep in a 13:32 13 minutes, 32 seconds nutshell I said if we did a strategic roll out in the next 5 years we pull out 60 Grand a year uh and uh in five years 13:42 13 minutes, 42 seconds you’re going to be earning some money while you’re going so we’re going to get 300,000 instead of a quarter of a million out of there but you you’re only going to pay 12,500 a year in tax times 13:51 13 minutes, 51 seconds 5 years you’re only going to pay 6,000 in tax instead of um having to pay a quarter of a million would you like to 13:58 13 minutes, 58 seconds do that yeah that sounds like a no-brainer but we hate paying tax any sooner than we have to I said you’re going to pay okay you’re going to pay 14:07 14 minutes, 7 seconds 60,000 now or you’re going to wait and pay a quarter of a million later it’s like the old Fram and auto Light commercial where an automobile mechanic would hold up an oil filter and say you 14:15 14 minutes, 15 seconds can pay me now and I’ll change your oil filter you can wait and pay me later and I’ll replace your engine and they finally got it okay and so uh I saved 14:24 14 minutes, 24 seconds them a quarter of a million of unnecessary tax because we actually resurrected deduction on their rental properties that allow 14:32 14 minutes, 32 seconds them to get the money out with no tax and so I saved them a quarter of a million of unnecessary tax uh they didn’t even have to pay 60,000 we 14:40 14 minutes, 40 seconds reduced it down to 20 down to zero the story is in the book uh you’re going to be blown away the next story in the book is the real estate landlord and he came 14:47 14 minutes, 47 seconds to me at age 70 and a half and he had 600,000 uh in his IR ra of 401ks now this was in 14:55 14 minutes, 55 seconds 2012 that 600,000 is what he had in the year 2000 and he saw that 600,000 in the 15:02 15 minutes, 2 seconds market go down to 360,000 twice in 2001 to 2003 after the 9/11 terrorist attacks and again in 2008 and it was barely back 15:11 15 minutes, 11 seconds to break even and he’s still going back to that advisor where he didn’t make anything in 12 years the adviser just 15:19 15 minutes, 19 seconds kept saying hang in there hang in there the market always comes back and the adviser says okay now you’re back to the 15:26 15 minutes, 26 seconds 600,000 just take rmds required minimum distributions well on 600,000 at his life expectancy that was 15:34 15 minutes, 34 seconds 24,000 a year in a 33% tax bracket he had to pay 8,000 every year in tax on that 24,000 he was netting 15:44 15 minutes, 44 seconds $116,000 after tax on his IR rais of 401ks to buy gas and groceries prescriptions and golf green fees now even though he didn’t need the money 15:52 15 minutes, 52 seconds that that’s pathetic okay that was the 4% rule we we roll the money out over a 16:00 16 minutes 5-year period we got the 600,000 out and and while we were getting it out of there we grew it to 16:06 16 minutes, 6 seconds 750,000 so he rolled out 150,000 bucks a year times 5 years we rolled out 16:13 16 minutes, 13 seconds 750,000 because we were managing his money way better than his advisor now simply he saw that if he pulled out 16:22 16 minutes, 22 seconds 150 Grand a year for 5 years he pulls out 100,000 and a 33% tax he’s paying 16:29 16 minutes, 29 seconds 50,000 in tax he’s only netting 100,000 to put into his IL bucket so far so good 16:37 16 minutes, 37 seconds so a net of 100,000 a year for five years he gets 500,000 in his I bucket and uh he knew he could earn at least 8% 16:45 16 minutes, 45 seconds what’s 8% on 500,000 in the IL 40,000 a year he could take out 4,000 a year 16:53 16 minutes, 53 seconds taxfree compared to 16,000 after tax it was a no-brainer he actually earned 10% 10% would be 50,000 how much more is 17:02 17 minutes, 2 seconds 50,000 than 16,000 well he also owned a whole bunch of rental properties uh rental homes and 17:09 17 minutes, 9 seconds he refinanced four of them and uh resurrected tax deductions he uh pulled out the equity in those rental Chapter 7: Real Estate and IUL Funding 17:17 17 minutes, 17 seconds properties put it into the iul and he was earning more than double the net cost of the mortgage he was making money hand over fist but the Strategic 17:25 17 minutes, 25 seconds byproduct that came along for the ride is uh we resurrected deductions that he had killed by paying down the mortgages 17:33 17 minutes, 33 seconds and that offset the entire 50,000 uh a year in tax and so we actually got out 17:41 17 minutes, 41 seconds 150,000 a year tax free for 5 years we got 750,000 out of his IR razor 401ks 17:51 17 minutes, 51 seconds taxfree that 750,000 in the I is generating 75,000 a year of tax-free 17:58 17 minutes, 58 seconds income compared to where if he left it in his IRAs he was experiencing 16,000 a 18:05 18 minutes, 5 seconds year what was your other half 16,000 a year or 75,000 we do this all the time uh the next example husband and wife 18:13 18 minutes, 13 seconds Physicians they came to us with 4.6 million in their iriser 41 case their uh advisor said well uh yeah they’re going 18:21 18 minutes, 21 seconds to pay a lot of tax but they can afford it I did an illustration you’re you’re going to pay 2.6 million at least in 18:30 18 minutes, 30 seconds taxes if you take this advisor’s advice uh postpone till 72 and take rmds they were flabber I said 2.6 18:38 18 minutes, 38 seconds million and the adviser just goes well they can afford 2.6 million I said well let’s ask them I said I can’t save you 2.6 million you you’ve painted yourself 18:46 18 minutes, 46 seconds into a tax trap here but I could save you about 1.2 million do you want to do that absolutely I saved them 1.2 million 18:55 18 minutes, 55 seconds of unnecessary tax that otherwise payable tax went into an ilul that 1.2 million has been generating 100,000 a 19:03 19 minutes, 3 seconds year of tax-free income for them they don’t need it’s using it for vacations uh their kids their grandkids College U 19:10 19 minutes, 10 seconds military religious missions all kinds of things instead of that money going down the drain in unnecessary tax they loved 19:19 19 minutes, 19 seconds the Strategic roll out the last example is we took a couple in California from the highest tax bracket they were in was 19:26 19 minutes, 26 seconds 40% down to a 0% tax bracket in 5 years when they came to us they had 6 million 19:33 19 minutes, 33 seconds in IAS a 401 case again their advisor was saying postpone defer take rmds when you get to be a72 instead they saw the 19:42 19 minutes, 42 seconds light uh they bit the bullet they paid uh 2 million in 5 years in tax on the 6 million they netted 4 million after tax 19:52 19 minutes, 52 seconds 4 million was 800,000 a year into their IL they ended up putting in 4 million ion in 4 years in one day that 4 million 20:01 20 minutes, 1 second doubled to 8 million in another 7 and A2 years when they finally retired they now have 8 million tax-free and it’s 20:09 20 minutes, 9 seconds generating 600,000 to 800,000 a year of growth they only need 300,000 a year to live on but they pull out $300,000 a Chapter 8: High Tax Bracket to 0% Tax Bracket 20:18 20 minutes, 18 seconds year and uh it’s it’s not showing up anywhere on their 1040 tax return they’re in a z% tax bracket the IRS knows they’re receiving it and they know 20:26 20 minutes, 26 seconds it’s taxfree one last example ex Le we had a couple come to us with 2.6 million saved in their irer 401ks they were 20:35 20 minutes, 35 seconds proud and I said way to go but on that 2.6 million they were U going to take 6% a year and so 6% on that was going to 20:43 20 minutes, 43 seconds generate 160,000 a year of income and they had another 40,000 coming from you know the school teacher pension or 20:50 20 minutes, 50 seconds Social Security I can’t remember which they were excited to have 200,000 a year of income and I said well I see a big 20:57 20 minutes, 57 seconds problem well what is it well that 200,000 all showing up on the front page of your 1040 tax return the rest of your life they said you mean there’s another 21:06 21 minutes, 6 seconds way and I said yeah where have you been I said I’ve been here all along you’ve sort of had blinders on because you were too busy making the money so let’s do a 21:14 21 minutes, 14 seconds strategic roll out you’re going to pay 54,000 or more a year in tax the rest of your life you’re only 21:21 21 minutes, 21 seconds nitting 146,000 after tax right now so in 5 years we did a strategic roll out 21:29 21 minutes, 29 seconds for 60% of that we took 120,000 of that 200,000 of income off of their 1040 tax return the IRS knows 21:37 21 minutes, 37 seconds they’re still receiving it but they know it’s taxfree it’s an IL okay now they’re actually getting more than 200,000 a year of income because we’re managing 21:45 21 minutes, 45 seconds their money way better but let’s just use apples apples on the same 200,000 of income they only have to pay 21,600 in 21:53 21 minutes, 53 seconds tax they’re netting more money we save them 32,400 and now because their their tax bracket 22:00 22 minutes would be higher uh out to life expectancy we have saved them between 800,000 to a million do we do this all 22:10 22 minutes, 10 seconds the time and so uh this is called a strategic roll out if you want to learn more and see examples I would recommend 22:19 22 minutes, 19 seconds you claim a free copy of my book the laser fund it’s been flying off of our warehouse shelves uh you can pay $20 to 22:26 22 minutes, 26 seconds $70 for it on Amazon if you do that thank you but I’ll get you a copy free simply click on the link below or go to 22:33 22 minutes, 33 seconds laser fund.com and you cont tribute a nominal amount towards the shipping and handling I require a little bit of skin in the game uh I’ll cover the rest of 22:41 22 minutes, 41 seconds that and I’ll pay for the book I will fire out a hard copy of this book to you via priority mail now it’s actually two 22:48 22 minutes, 48 seconds books in one this side is 200 Pages 14 chapters with all the charts and graphs if you’re a left brain learner if you’re a right brain learner and you learn more 22:57 22 minutes, 57 seconds by stories and examples you flip it over and read this one about 100 Pages 12 chapters with 62 actual client stories if you want to use both the left brain 23:06 23 minutes, 6 seconds and the right brain your whole brain uh read both of these books uh but when you’re in there claiming your free copy Chapter 9: Want to learn more? Then get a free copy of my books! 23:13 23 minutes, 13 seconds if you like to listen and learn and watch and learn there’s audio and video formats there’s even an 18-hour master 23:21 23 minutes, 21 seconds class that you can invest in that’s what our affluent clients invest in because they know more about this than 99% of 23:29 23 minutes, 29 seconds uh insurance agents do uh they’re educated when they come to us and so that’s why they want IL that will accommodate you know 12 million 50 23:37 23 minutes, 37 seconds million $100 million getting back to you um if you’re uh a member of the public and you want 23:46 23 minutes, 46 seconds to make sure whoever you talk to knows what they’re doing while you’re in there claiming your free copy you can schedule a a free consultation no cost no 23:55 23 minutes, 55 seconds obligation with a certified iul professional these are the top onet of 1% of ilul agents who know they have passed a 24:03 24 minutes, 3 seconds stringent exam and I know that they know how to do it right uh you’re going to want to make sure it’s done right and so 24:10 24 minutes, 10 seconds you can do that no cost or obligation if you are an agent and you want to learn how to become certified then uh click on 24:19 24 minutes, 19 seconds the link and you can go to I insiders.com and we’ll show you how you can go through the certification process 24:26 24 minutes, 26 seconds which is not easy but it’s worth it this is about you whether you are a a client 24:33 24 minutes, 33 seconds that wants to optimize assets and not outlive your money or whether you’re a professional and you want to actually be a professional
_______________________
Frequently Asked Questions (FAQs)
Q: Can I do a strategic rollout on my own? A: Strategic rollouts can be complex, and they require expertise to minimize the impact of taxes while maximizing your opportunity for tax-advantaged growth. Be sure to consult a professional who is an expert in strategic rollouts. If you’re moving your money to an IUL, you specifically need to work with a licensed insurance professional, and look for one who is an expert in structuring and optimizing IUL.
Q: Can I really access my IUL LASER Fund cash value tax-free? A: Yes—when structured and accessed correctly, you can access your IUL LASER Fund’s cash value via policy loans, with no tax reporting under current law, supporting tax-free retirement income.
Q: Is there any risk of losing money due to market volatility in a LASER Fund? A: The IUL LASER Fund strategy is built for safety—your principal is protected from market losses and credited interest can only go positive or zero, depending on market performance.
Q: What makes an IUL “properly structured” or “max-funded”? A: A properly structured, max-funded IUL LASER Fund is optimized to minimize costs and maximize potential cash growth, staying within IRS guidelines to preserve tax advantages.
Q: Where can I learn more about the IUL LASER Fund or start my own policy? A: Order our comprehensive “The LASER Fund” book for free (you just cover shipping) at laserfund.com, attend a virtual educational event, or connect with a certified expert by clicking here.
Still have questions? Want to unlock your own tax-free retirement strategy?
Connect with an IUL LASER Fund specialist today: Get started now.
 Most people spend decades saving for retirement inside accounts like a 401(k), traditional IRA, or 403(b). These accounts feel like a win because they let you delay paying taxes on the money you contribute. But there’s a catch that many savers don’t fully appreciate until it’s time to actually use the money. Every dollar you pull out later is taxable, and nobody knows what tax rates will look like down the road — and most people think they’ll be higher.